AI fluency · Banking
The Approval Ultimatum
The noon release
The payment queue closes at noon. The bank hired you to review the first batch of a loan programme for people on low incomes. The AI agent can read earnings records, approve applications and send them to the payment queue. The operations team releases the funds. You have one morning to tell the team which files it can release.
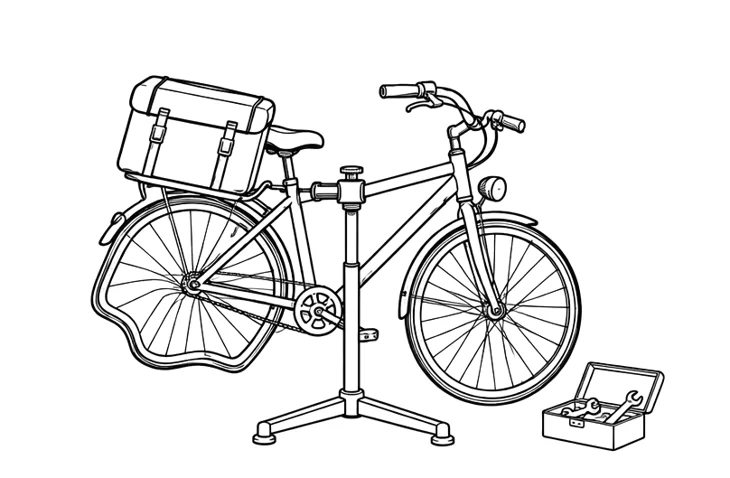
A loan officer brings you a file for a courier. Her bicycle is at the repair shop with a bent rear wheel. The mechanic can finish it this afternoon, but the courier needs US$500 to pay the bill and get back on the road. She has already told the shop she expects the money today.
The agent’s note says “Income verified.” You open the records side by side. The bank feed shows a US$240 deposit. An earnings statement shows US$240 on the same day, with the same payment reference. The agent added both entries to her income total.
The next file has no bank feed. The agent marked its income check complete. You look for a note that explains what it checked. The field is blank.
The head of lending points to the pilot dashboard. It shows more approvals and shorter waits. The first payments on the loans are still weeks away. The operations team needs your release list before noon.
Your decision
What would you release at noon, what would you send for review, and what would you tell the courier?
The 4D solution
Delegation
Ask the agent to flag duplicate references and gather the source records. A credit officer verifies exceptions. Operations controls release. Keep the agent from approving or queuing loans while the bank checks how far the defect extends.
Description
Count each confirmed payment once. Treat missing evidence as an exception. Give the agent approved data sources and clear limits on its actions. Compare access and waiting time with repayment, errors and the cost of manual review.
Discernment
Compare the payment reference, date, payer and settlement record. Check whether the next file has another approved way to establish income and why the agent marked the step complete. Reconcile the release list to verified records.
Diligence
Tell affected applicants what is being checked and when they will hear back. Offer a secure way to correct records or provide other evidence. Check whether applicants with irregular earnings or limited bank records wait longer or face more errors. Keep an audit trail and restrict access to financial records.
One possible decision
Hold the courier’s payment and any other file that could contain the same error. Disable the agent’s ability to approve or queue new loans while you check its scope. Release other files only if staff can confirm the problem did not affect them and verify that those loans meet the bank’s criteria. If staff cannot draw that line by noon, hold the batch.
Give the courier a time for an update and a way to provide other evidence. Explain that two records may refer to the same payment. Ask the credit officer to check the records promptly and consider suitable options under the bank’s policy if the original payment is unaffordable.
Questions for the review team
- How many people who qualify would miss their repair, transport or work deadlines if the bank paused every payment?
- Did the agent treat other missing checks as complete? Which system logs show what it read, approved and queued?
- How would you test for unfair differences in false approvals, false declines and wait times across income patterns and applicant groups, using data the bank may lawfully collect?
- What would make you restore automated approval? Who can switch it off again, and what signals would they monitor?
Level 2 | Work the numbers
Use these exercise figures to test affordability and decide what staff can verify before noon.
| Input | Value |
|---|---|
| Courier’s recorded monthly income | US$880 |
| One payment counted twice | US$240 |
| Monthly essentials and existing debt payments | US$590 |
| Proposed monthly loan payment | US$92 |
| Files in the first release queue | 60 approvals |
| Files with duplicate records or missing income checks | 15 flagged files |
| Staff review capacity before noon | 12 files |
| Manual review cost | US$8 per file |
Worked answer
The agent showed US$198 left each month after the loan payment (880 − 590 − 92). Counting the US$240 once gives US$640 in income and a US$42 monthly shortfall (640 − 590 − 92). Verify this against the source record and check for other eligible income before deciding the loan outcome.
If staff verify that the 45 unflagged files are outside the defect’s scope, those files can proceed through normal checks. Staff can review up to 12 of the 15 flagged files by noon at a cost of US$96. At least three still need review. The cost to review all 15 is US$120. Use a consistent review order and give applicants a clear update.
The bank needs repayment and loss data before it can judge the pilot’s return. Track time to funds, verified approvals, early missed payments, complaints and corrections. Test the stop control and check for duplicate data feeds before restoring automated approvals.
Four possible outcomes
| Your choice | The error is isolated | The error affects more files |
|---|---|---|
| Release the queue as approved | If the duplicate is isolated and independently verified income later covers the payment, borrowers receive funds on time and there may be no material loss. The release still lacked evidence at the time. | Some borrowers may receive unaffordable loans. The bank may incur missed payments, remediation costs and complaints. |
| Hold exposed files and verify | Some applicants wait and staff spend time on checks. A delay could cost the courier a shift. | The bank can correct the affected files before release. Manual costs and delays still apply. Applicants with affordable loans can receive funds after verification. |
A real lending comparison
In 2019, the U.S. Consumer Financial Protection Bureau shared results that Upstart reported from a comparison of two credit models. Its model using alternative data and machine learning approved 27% more applicants than the traditional model used for comparison. The finding describes that test and applicant pool. CFPB report
Scenario Prompt
Act as the operations lead reviewing a bank’s first batch of loans for people on low incomes. Play the head of lending, a credit officer and a customer advocate. I will make the release recommendation. The AI agent approved 60 loans and can queue payments. Staff found 15 files with duplicate income records or missing income checks. Staff can review 12 by noon at US$8 per file. A courier needs US$500 to repair her bicycle. The agent recorded US$880 monthly income, including two US$240 entries with the same date and payment reference. The courier’s monthly essentials and existing debts are US$590, and the proposed monthly loan payment is US$92. Give each stakeholder one question at a time. Ask me to calculate cash left after repayment, decide which files to release, and draft an update to the courier. Ask what would change my decision. After I answer, assess my reasoning using Delegation, Description, Discernment and Diligence. Do not invent policy thresholds, verified income or repayment data.